Loan Calc Hub
- 3.6
- Rating
- 1.00M
- Installs
- Free
- Price
 Analysis by App-foxy
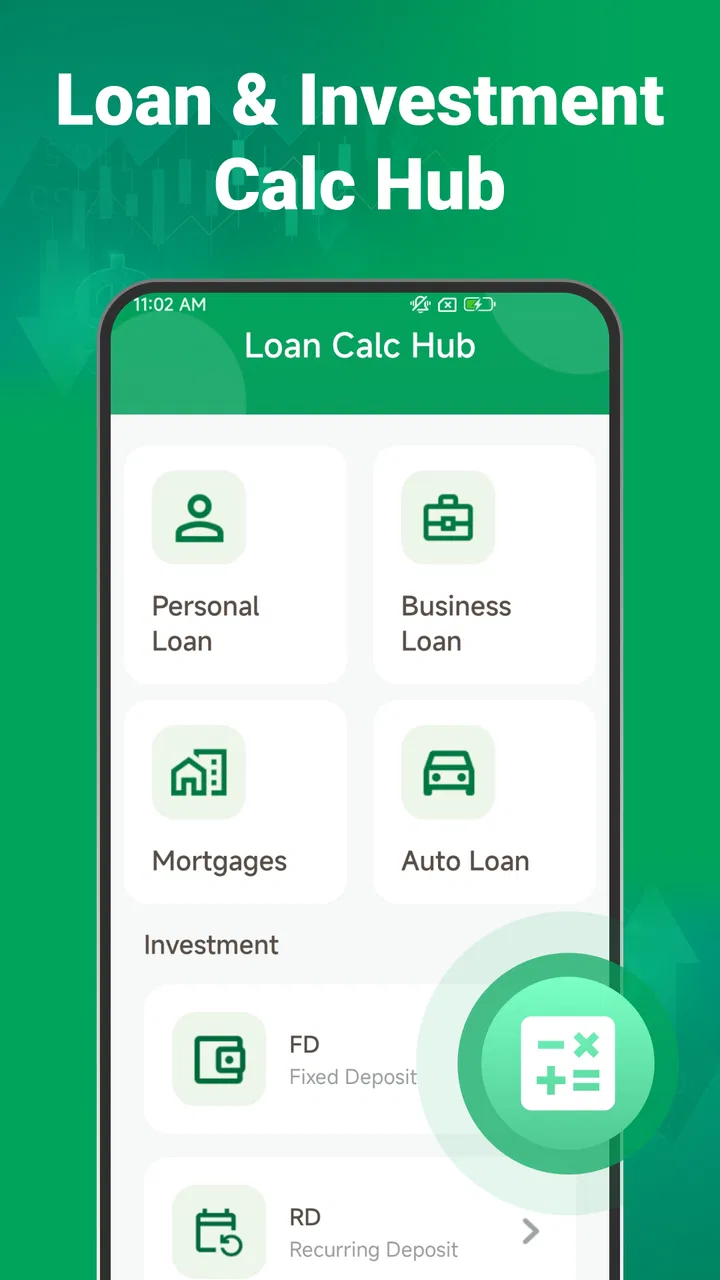
When I first opened Loan Calc Hub, I understood its appeal almost immediately: it turns several money questions into quick calculations instead of forcing me to build a spreadsheet from scratch. The app sits in the finance category and focuses on loan repayments, fixed deposits, and recurring investments. That is a narrower job than a full budgeting app, but the narrow focus can be useful when I need an answer before making a financial decision.
My overall impression is that this is best treated as a practical calculator rather than a complete financial companion. It can help me explore possibilities, compare scenarios, and avoid rough mental arithmetic. It does not replace a lender’s official quotation or a careful investment plan, but it can make the first stage of research much less intimidating. The important question is whether those occasional calculations are valuable enough for me to keep the app installed after the first week.
Useful on day one, but only when I bring a clear question
The first-week appeal comes from how easy it is to understand the purpose. I do not need to learn a complicated dashboard or enter my entire financial life. I can approach it with one question: “What might this loan cost each month?” or “What could regular deposits look like over time?” That directness is a genuine strength for anyone who wants a quick estimate without committing to a larger money-management system.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



I found the loan side most immediately useful for comparing possibilities before contacting a lender. For example, if I were considering a used car, I could test a few borrowing amounts and repayment periods to see whether the monthly commitment feels realistic. That does not tell me whether I will be approved, and it does not account for every charge a lender might add, but it gives me a sensible starting point. I would rather discover that a proposed payment feels uncomfortable in a calculator than after beginning an application.
The app’s other focus areas make it more useful than a single-purpose loan calculator. Fixed deposits and recurring investments involve different habits and expectations, so having them together encourages me to look at borrowing and saving as connected decisions. If I am thinking about taking on a new payment, I can also consider whether I am still able to maintain a regular saving contribution. That side-by-side thinking is one of the more valuable ideas behind the app.
There is also a psychological benefit to using a dedicated calculator. A spreadsheet can be more flexible, but it asks me to decide which formulas, labels, and assumptions to use. Loan Calc Hub lowers that initial barrier. For a person who is comfortable with everyday phone apps but not with financial formulas, that simplicity may be the reason they actually check the numbers instead of guessing.
Still, I would not mistake a clean estimate for financial advice. The result is only as useful as the figures I enter and the assumptions behind them. Interest conventions, compounding methods, fees, taxes, and payment schedules can change the real outcome. My practical tip is to use the app for comparison rather than certainty: test a conservative case, a comfortable case, and the most optimistic case before making a decision.
A realistic everyday workflow
Imagine I am planning a recurring investment while also considering a personal loan. I would begin by entering the proposed loan details and noting the estimated repayment. Then I would run a recurring-investment scenario using an amount I could genuinely set aside after bills, rather than choosing an attractive figure just to produce a larger future value. Finally, I would compare the two results with my existing monthly commitments.
That workflow reveals a trade-off that a basic store description does not explain: the app is more useful when I use its calculators together, even though each calculation is separate. The value is not only in the individual result. It is in forcing me to view a payment, a deposit, and a regular contribution as competing demands on the same monthly budget.
Another helpful habit is to write down the assumptions beside any result I want to remember. A number without its interest rate, duration, contribution amount, or deposit value can become misleading later. Since this is a calculator rather than a personal finance journal, I would not rely on it as my only record. A note on my phone or a small spreadsheet can preserve the context while the app handles the quick recalculation.
Where the value holds up from month to month
After the novelty fades, the app’s lasting value depends on whether I regularly face decisions that need estimates. Someone comparing loans, planning a deposit, or adjusting a recurring contribution may return to it several times during a financial planning period. For that user, the focused design can remain useful because the same questions often need to be tested again when the amount, term, or goal changes.
It is particularly handy during a change in circumstances. A salary adjustment, a new rent payment, or an upcoming large purchase can make an old plan unsuitable. Instead of assuming that a previous monthly contribution still works, I can recalculate it. This makes the app more valuable as a check-in tool than as something I open every day.
That distinction matters. I do not see a reason to launch a calculator like this daily unless I am actively planning a financial move. Its recurring value is occasional and decision-based, not habit-forming in the same way as a spending tracker. For me, that is not a flaw, but it does mean the app has to earn its place through reliability and convenience rather than constant engagement.
The app is free, which makes keeping it available for those occasional moments easy. Its content rating is Everyone, so it is approachable for a broad audience, including people who are just beginning to understand borrowing and saving calculations. The developer is AppDsgnur, and the current version is 1.2.0.0. I would still check the inputs carefully every time, because a newer version number does not turn an estimate into an official financial document.
Its audience size suggests that it has reached a substantial number of Android users, with over a million installs, while the average rating is 3.6 from around a thousand ratings. I read that combination as a sign of practical interest rather than universal satisfaction. Many people are willing to try a focused finance calculator, but the middling score also supports my cautious view: it may solve a specific problem well enough without being the perfect tool for every user.
How it compares with familiar alternatives
The usual alternative is a search engine result or a lender’s own calculator. A lender’s tool is normally better for checking that institution’s actual products, rates, fees, and repayment rules. However, it can be less convenient when I am comparing several possibilities from different providers. Loan Calc Hub is more neutral for early exploration because it is not tied, in my experience of its purpose, to one borrowing application.
A spreadsheet is the stronger option when I need a detailed model. I can create multiple rows, add fees, record actual payments, and preserve a history of changing assumptions. The cost is effort. Loan Calc Hub wins when I want a fast answer without designing a worksheet, while a spreadsheet wins when the decision is large enough to justify a permanent record.
A full budgeting app is better for tracking income, expenses, categories, and account balances over time. Loan Calc Hub is not the tool I would choose to understand where all my money goes. Its strength is forward-looking estimation: what a loan might cost, what a deposit might grow to, or what regular investing could produce under the selected assumptions. Choosing between the two depends on whether I need a forecast or a complete financial overview.
For investment questions, I would be especially careful with comparisons. A recurring-investment estimate can help me understand the effect of contribution size and time, but it should not be read as a promise. Actual returns can vary, and the app’s output should be one planning input rather than the basis for a guarantee. If I need risk analysis, product research, tax treatment, or portfolio management, I would use a specialized service instead.
The small habits that make the calculations more trustworthy
My first tip is to run sensitivity checks instead of accepting one attractive result. Change one input at a time and observe how the estimate responds. For a loan, I would vary the amount or duration. For a recurring investment, I would test a contribution that is easy to sustain rather than one that would strain my budget. This turns the app from a number generator into a simple decision-testing tool.
My second tip is to separate affordability from possibility. A calculator may show that a payment fits mathematically, but that does not mean it fits comfortably after food, housing, emergencies, and irregular expenses. I would calculate the result, then leave room for real life. This is where a dedicated calculator can tempt users into false precision if they focus on the displayed answer instead of their wider budget.
My third tip is to use it before, not after, a conversation with a bank or investment provider. I can arrive with clearer questions about rates, fees, payment timing, and the assumptions used in the official illustration. The app cannot answer those provider-specific questions, but it can help me recognize when an explanation or quotation deserves a closer look.
A fourth useful habit is to repeat a calculation when the goal changes, not merely when the calendar changes. Monthly use for its own sake adds little. Recalculating after a job change, a new obligation, or a revised savings target is more meaningful. That approach keeps the app from becoming another notification-driven habit and gives it a practical role whenever my circumstances move.
Where the routine starts to feel tiring
The main source of fatigue is repetition. If I need a complete picture of my money, I may end up entering similar information in several places: the calculator, a budget, a lender’s form, and perhaps a personal note. The app saves time at the individual calculation stage, but it does not remove the broader work of collecting accurate figures and keeping assumptions organized.
Another point of friction is the gap between an estimate and the final product. A result can look precise even when the real agreement uses different fees, timing, or interest rules. I would not use the app as the final checkpoint before signing anything. Its best role is to tell me whether a proposal deserves deeper investigation, not to certify that the proposal is correct.
Users who want automatic tracking may also lose interest. This is not where I would look for the ongoing visibility of a budget dashboard. Someone who wants spending alerts, account connections, transaction categorization, or a long-term record will likely be better served by a full personal-finance application. Loan Calc Hub makes more sense for someone who prefers entering a scenario manually and receiving a focused estimate.
The lack of a daily reason to open it can be both a limitation and a benefit. It will not necessarily become a central part of my phone routine, but it also does not need to demand attention. I would keep it installed during a period of borrowing or saving decisions, then remove it if my financial questions have settled. That is a healthier standard than expecting every finance app to become a permanent habit.
There is also a learning curve in interpreting results responsibly. The buttons and fields may be simple, but the financial concepts behind them are not always simple. A first-time borrower could still misunderstand the difference between a monthly payment and the total cost of borrowing. I would advise new users to look beyond the easiest number to notice and ask what assumptions produced it.
Who should keep it installed
I would recommend it to a person who wants a free, focused way to compare loan repayments, fixed-deposit possibilities, and recurring-investment scenarios. It is a good fit for early-stage planning, especially when I am not yet ready to choose a provider or build a detailed spreadsheet. It can also help someone prepare for a useful conversation with a bank, family member, or financial adviser.
I would be less enthusiastic for a user who wants a complete financial command center. If the priority is tracking every expense, monitoring accounts, managing a portfolio, or maintaining a detailed history of actual payments, another category of app is more appropriate. I would also skip relying on it alone for a major financial commitment where fees, taxes, variable rates, or investment risk materially affect the decision.
The free price lowers the barrier to trying it, and the Everyone rating makes it broadly approachable. Still, accessibility should not be confused with simplicity of the underlying decisions. I would introduce a younger or inexperienced user to the app alongside a discussion about interest, affordability, and risk rather than letting a single result guide them.
My long-term verdict
Loan Calc Hub earns lasting space on my phone when I am actively comparing borrowing and saving choices. Its strongest quality is focus: I can move from a vague financial question to a concrete estimate without setting up a large system. The combination of loan, fixed-deposit, and recurring-investment calculations also encourages a more balanced look at monthly commitments.
Its long-term weakness is that the value arrives in bursts. Once I have made a decision and my figures stop changing, I may not need it often. That is not a reason to dismiss it; it simply means I judge it as a dependable utility, not a daily finance companion. The maintenance burden is low because I can return when needed, but maintaining good financial decisions still requires checking assumptions outside the app.
My final recommendation is measured but positive. Install it if you want quick scenario comparisons and are willing to verify important details with official sources. Use it to test affordability, prepare questions, and compare alternatives. Do not use it as a substitute for a lender’s final calculation, a detailed budget, or investment advice. The app earns its place through useful moments, not constant attention.
FAQs for Loan Calc Hub
01What is Loan Calc Hub used for?
Loan Calc Hub is designed to help users estimate the cost of borrowing before applying for a loan. You can enter details such as the principal amount, interest rate, repayment period, and payment frequency to view estimated installments and total repayment. It is useful for comparing scenarios, planning a budget, and understanding how changing loan terms may affect affordability.
02Does Loan Calc Hub provide real loan offers or approve applications?
No. Loan Calc Hub should be treated as a calculation and planning tool, not as a lender or loan broker. The figures shown are estimates based on the information entered and do not represent an approval, guaranteed rate, or binding offer. Actual terms may vary depending on the lender, credit history, fees, taxes, insurance, and other conditions included in a formal loan agreement.
03How accurate are the calculations in Loan Calc Hub?
The results can be useful for general financial planning when the entered information is correct, but they should not be considered a final repayment schedule. Accuracy depends on the calculator’s available formulas and whether it accounts for factors such as compound interest, additional charges, variable rates, or irregular payments. Always confirm the final figures directly with the lender before making a decision.
04What information do I need to use Loan Calc Hub?
Most calculations require the amount you want to borrow, the annual interest rate, and the loan duration. Depending on the calculation type, you may also need to select a payment frequency or enter fees and an initial deposit. Having realistic figures available makes the estimate more helpful. If you are unsure about a rate or charge, check the lender’s documentation rather than guessing.
05Is Loan Calc Hub safe, and should I enter personal financial information?
A loan calculator generally needs only numerical information to estimate repayments, such as an amount, rate, and term. Avoid entering passwords, bank account details, identity numbers, or other sensitive information unless the app clearly explains why it is required and how it is protected. Before downloading, review the app’s privacy policy, permissions, developer information, and any data-sharing disclosures available on the store page.
Pros
- Calculates loan payments quickly with flexible term and interest inputs.
- Supports comparisons between different loan scenarios.
- Useful for budgeting before applying for credit.
- Simple interface makes it accessible to first-time users.
- Helps estimate total interest and repayment costs.
Cons
- Results depend entirely on the accuracy of the entered figures.
- May not include lender-specific fees
- taxes
- or insurance costs.
- Does not guarantee approval or reflect personalized loan offers.
- Limited value for complex loans with changing interest rates.
- Users should verify calculations against official lender documents.

Loan Calc Hub
Gallery